
Two Innovative Models Expanding Affordable Housing in the Southeast
November 02, 2026
Housing is the single largest expense for most families, placing pressure on household budgets especially among low- and moderate-income renters. Data from the Southeastern Rental Affordability Tracker highlight the shortage of affordable housing available for low- and moderate-income renters.1 In Sixth District states, for every 100 renter households making at or below 50 percent of area median income, only 49 units are available, resulting in a total deficit of over 1.2 million units.2
Against this backdrop, communities across the Southeast are developing strategies to produce, preserve, and extend housing affordability by leveraging existing tools in the housing finance toolbox like the Low Income Housing Tax Credit (LIHTC).3 LIHTC remains the largest source of financing for the development and preservation of affordable rental housing.4 Since 2008, LIHTCs have contributed to the financing of approximately 240,000 units in roughly 2,700 developments across Sixth District states.5 LIHTC supports the affordable housing ecosystem throughout its lifecycle, from enabling construction and preservation efforts to shaping opportunities as affordability periods expire.6
Given LIHTC's importance in the affordable housing landscape, this Partners Update discusses two regional efforts that advance strategies for preserving affordability, including approaches to increasing unit production and mitigating the impact of expiring affordability requirements. These two initiatives emerged from insights shared during a recent convening of community advisers, where leaders from across the Southeast helped the Atlanta Fed deepen our understanding of the economic challenges households are navigating today and practical solutions to foster greater economic opportunity. The first effort is the Jacksonville Growth and Affordability Partnership Fund (Jax GAP Fund), which is using gap financing to make new multifamily developments financially feasible in Jacksonville, Florida, and help address supply deficits identified across the region. The second effort is HOPE Credit Union/Hope Enterprise Corporation's Year 16 Initiative, an initiative converting expiring LIHTC units into affordable homeownership opportunities for longtime renters across rural Deep South communities.7 Together, these case studies show how communities can leverage LIHTC to expand affordable housing opportunities and advance economic resilience in communities across the Southeast.
How Jacksonville is financing the gap to catalyze affordable rental supply
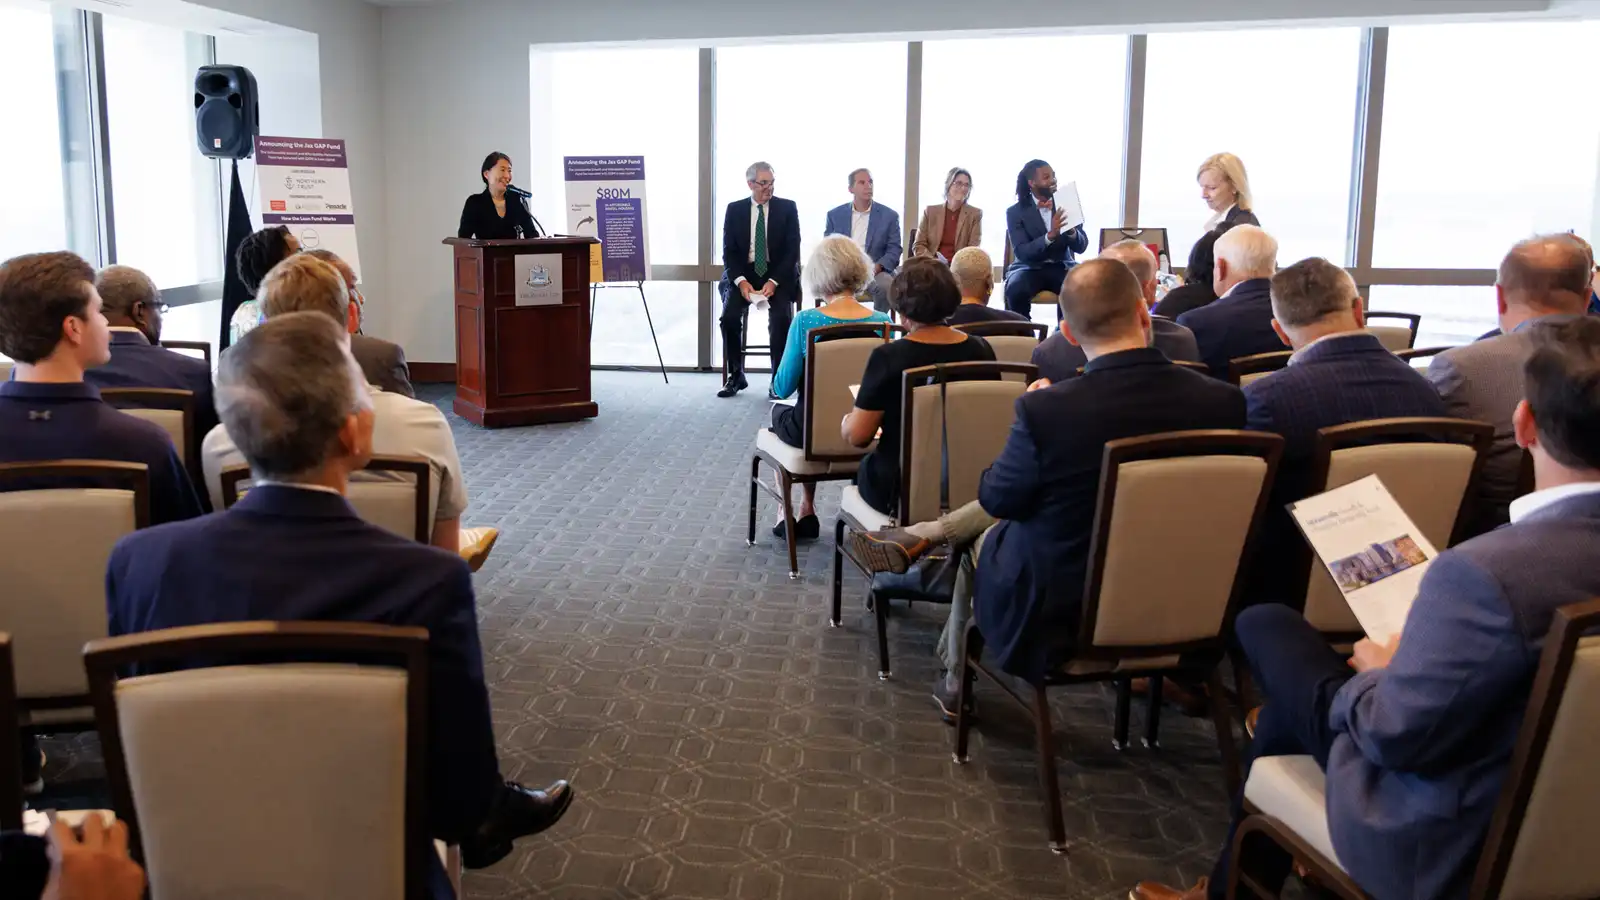
Jacksonville's rental market has faced sustained pressure for years.8 According to the Southeastern Rental Affordability Tracker, roughly 54 percent of renter households in Jacksonville are cost-burdened, meaning they are paying more than 30 percent of their income for housing. For every 100 renter households making at or below 50 percent AMI, only 37 units are available, leaving a shortage of affordable housing for low-income renters. Developers in the region recognize the need for more affordable rental housing, but limited federal resources constrain their ability to assemble viable capital stacks. State housing finance agencies allocate LIHTC awards to qualified developers of affordable rental housing projects, and because the nine percent tax credit is a highly competitive process, Duval County (where Jacksonville is located) is typically allocated only one nine percent tax credit award per year.9 As a result, most developers rely on four percent tax credits which provide lower subsidies and require more layered financing to make projects financially viable.10 The Jax GAP Fund is a local innovation designed to close financing gaps in affordable housing development. Launched in August 2026, the $20 million loan fund brings together private, philanthropic, and community investors to incentivize the financial feasibility of multifamily rental development supported by four percent LIHTCs and other hard-to-finance projects.
Structured as a pooled loan fund, the Jax GAP Fund is administered by Self Help Ventures Fund, a Community Development Financial Institution (CDFI) that handles both underwriting and origination. Anchor investments from lead investor Northern Trust ($10 million), the Jessie Ball duPont Fund ($5 million), The Community Foundation for Northeast Florida ($3 million), and Pinnacle Financial Partners ($2 million) allow the fund to provide both gap financing for affordable housing projects and bridge financing to help developers secure land in competitive markets. Chris Crothers, director of impact investing at the Jessie Ball duPont Fund, shared that "we started a conversation asking, how can we increase access to capital? Then we realized it's not necessarily a lack of capital problem. It's about access to the right kind of capital."11 By combining investor funds into a single vehicle, the goal of this model is to provide flexible, low-cost capital in the capital stack, which is necessary to make LIHTC deals viable. The $20 million pooled fund is designed to leverage the tax credit and stimulate $80 million in new affordable multifamily housing development, with repayments recycling capital to investors over a 20 year repayment period.
By offering both gap financing and bridge loans for land acquisition, the fund helps developers compete in fast moving markets and fill critical capital stack gaps that often derail four percent LIHTC projects. With the two philanthropic foundations taking a first-loss position, the model attracted additional private investment. Investors anticipate that future iterations of the fund will attract public dollars to de-risk other private investment and create a competitive environment for new developers interested in the Jacksonville affordable housing market. As Florida's first private, local equivalent of the State Apartment Incentive Loan, the Jax GAP Fund is designed to meet developer needs, reduce financing barriers, and accelerate affordable rental production across Northeast Florida.
From expiring LIHTC rental units to affordable homeownership
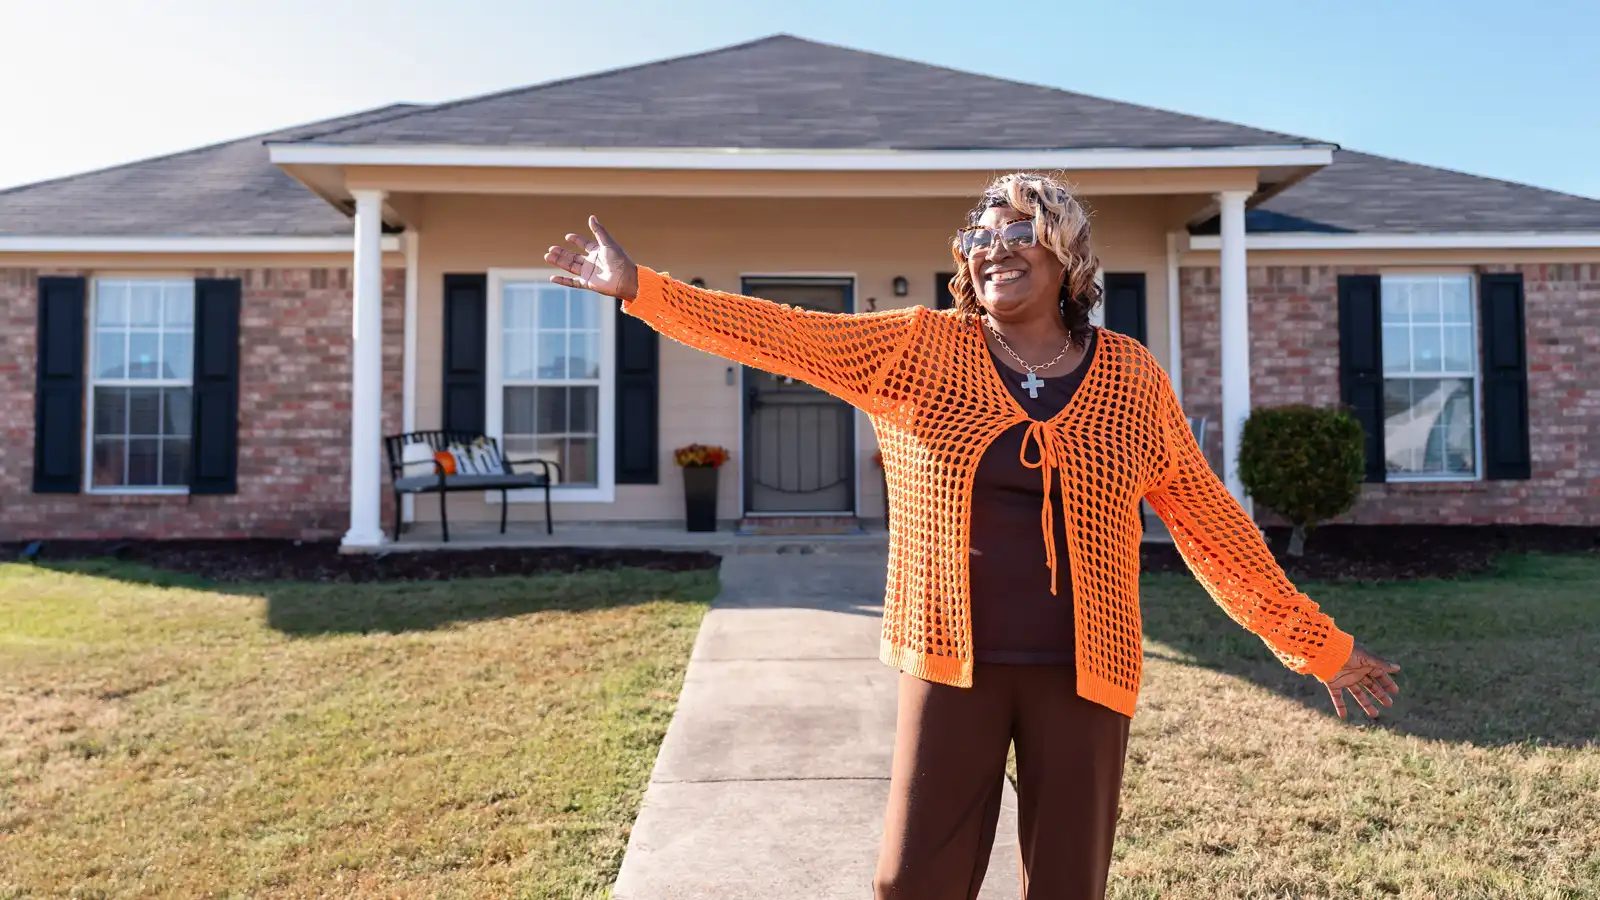
Across the South, thousands of single-family homes built using LIHTCs are reaching the end of their mandated 15-year affordability period.12 HOPE's Year-16 (Y-16) initiative emerged as a pathway through this transition, working with LIHTC developments built with lease-purchase provisions, enabling long-term renters to buy their homes at year 16. Mississippi alone has more than 5,000 LIHTC single-family units eligible for lease purchase conversion, and other states across the Sixth District have similar pipelines.13 The Y-16 initiative is a promising model demonstrating how expiring LIHTC units can do more than preserve affordability; they can open the door to sustainable homeownership and wealth building for families who have often lived in these homes for years.
As a mission-focused CDFI credit union, loan fund, and policy institute, HOPE is uniquely positioned to pilot this model in the South with their LIHTC experience, deep relationships in rural communities, and their capacity to provide mortgages to traditionally underserved borrowers. The Y-16 model blends targeted financial tools with intensive homeowner preparation, creating a mechanism tailored to the realities of rural LIHTC residents. HOPE deployed it's long-standing successful in-house mortgage product with flexible underwriting standards to expand homeownership in the Deep South, and in the instance of Y-16 integrating the use of successful rental-payment history, an inclusive approach that recognizes the strength of borrowers who have consistently paid rent but may not have traditional credit profiles, for these relatively small mortgage loans.14 Jena Reed, HOPE's vice president of community and economic development, has said about the program, "We're demonstrating how the mortgage and underwriting system can work better, in a more inclusive way, for people it currently leaves out."15 The lending is paired with affordability supports, including down-payment assistance, to keep purchase prices within reach. At the same time, HOPE provides a five-module homeownership readiness curriculum developed with community partners, introducing the opportunity to purchase, providing traditional homeownership counseling, and post-purchase considerations such as heirs' property and succession planning, all critical for long-term stability of communities. This wraparound support ensures residents are prepared not just to buy a home, but to sustain it.
Y-16 also reflects the complexity and flexibility of LIHTC transitions. Buyers must be current tenants and current on rent, and participation varies by development. In some communities every household has elected to buy; in others, some residents may continue renting during the extended-use period or developers may re-syndicate remaining units to maintain affordability. HOPE supports these pathways by working with developers, the state housing finance agency, and residents to ensure the original lease-purchase promise is fulfilled. As of this writing, 73 rural households have already become homeowners through the Y-16 initiative. According to HOPE, the average home appraises at about $100,000, thus enabling long-term renters to build wealth through homeownership. HOPE estimates about 10,000 units eligible for such conversion across the Deep South.16
The continuum of impact
Taken together, these case studies illustrate how Southeastern communities are leveraging LIHTC as a catalyst to activate complementary community-driven partnerships, strategies, and innovations. One model strengthens rental unit production through flexible capital, while the other transforms expiring units into homeownership opportunities. These models demonstrate how communities can build upon LIHTC's platform to deepen economic resilience and expand access to stable, affordable housing. Together, they reveal a continuum of impact—one that starts with a new development breaking ground and continues as families build wealth in homes they've long called their own.
The views expressed here are those of the author’s and not necessarily those of the Federal Reserve Bank of Atlanta or the Federal Reserve System. Any remaining errors are the author’s responsibility.
The Federal Reserve Bank of Atlanta does not provide grants or funding to the general public or to partner organizations. We do not endorse or make any representations as to the suitability of partner organizations, their products, or their programs, and we do not advise on distribution of funds by partners.
The Federal Reserve Bank of Atlanta's Community and Economic Development function supports the Central Bank's mandate of stable prices and maximum employment by helping improve the economic opportunity of low- and moderate-income (LMI) individuals and underserved places for a stronger economy for all Americans. Community development is one of the Federal Reserve's core functions and this responsibility is rooted in its mandates from Congress. Partners Update articles address community and economic development trends, issues, and events. Find more research, use data tools, and sign up for email updates at Community Economic and Development.
- 1 Board of Governors of the Federal Reserve System, "Report on the Economic Well-Being of US Households in 2025–May 2026," (Board of Governors, updated May 26, 2026).
- 2 Federal Reserve Bank of Atlanta Southeastern Rental Affordability Tracker, query for "Table Surplus/Deficit of Affordable and Available Units in Sixth District States per 100 Rental Households," accessed August 24, 2026. Authors' calculations of Sixth District states including all of Alabama, Florida, Georgia, Louisiana, Mississippi, and Tennessee.
- 3 LIHTC awards come in two forms: 1) the competitive nine percent credit which offers a higher subsidy often used for new construction; and 2) the four percent credit, which is paired with tax-exempt bonds and typically supports preservation or lower-subsidy projects. Because the four percent credit provides a more limited subsidy, deals often rely on more complex and layered capital stacks to make these projects financially feasible. See Mark P. Keightley, "An Introduction to the Low-Income Housing Tax Credit," Congressional Report RS22389 (US Congress, August 24, 2026).
- 4 US Department of Housing and Urban Development, Office of Policy Development and Research, query for "LIHTC Database | Low-Income Housing Tax Credit Program Properties and Tenants Data," HUD User, revised May 28, 2026; accessed August 24, 2026.
- 5 Dontá Council and Grace Johnsen, "What Are the Patterns for Low-Income Housing Tax Credit Use Across the Southeast?," Partners Update (October 05, 2026). Authors' calculations of Sixth District states including all of Alabama, Florida, Georgia, Louisiana, Mississippi, and Tennessee.
- 6 LIHTC properties typically have a 30-year affordability period made up of the initial 15-year compliance period, followed by the extended-use period which is generally an additional 15 years barring state housing finance agencies' extended compliance periods. LIHTC properties can undergo re-syndication for new credits that restart the compliance period. See Frances Torres, "Preserving Long-Term Affordability in LIHTC Housing," (Bipartisan Policy Center, May 17, 2023).
- 7 The Hope Enterprise Corporation's geographic reach includes Alabama, Arkansas, Louisiana, Mississippi, and Tennessee.
- 8 "Affordable Housing Initiatives," First Coast Connect, WJCT News 89.9 (April 6, 2026).
- 9"Jacksonville Growth and Affordability Partnership (GAP) Fund: A Private-Philanthropic Partnership is Piloting a Replicable Model for Financing Affordable Housing," (Jessie Ball duPont Fund, 2026), PDF.
- 10 Ibid.
- 11 Chris Crothers, private communication, Teams meeting 08/21/2026.
- 12 Hope Policy Institute, "Securing the American Dream: Advancing Homeownership in the Deep South through Expiring LIHTCs" (March 16, 2026).
- 13 Ibid.
- 14 Nicole Gudzowsky, "From LIHTC to Homeownership: Innovation Gains Ground in the Deep South" (Enterprise Community Partners, July 7, 2025).
- 15 Ibid.
- 16 Diane Standaert, private communication with author, Outlook email 10/27/2026.